
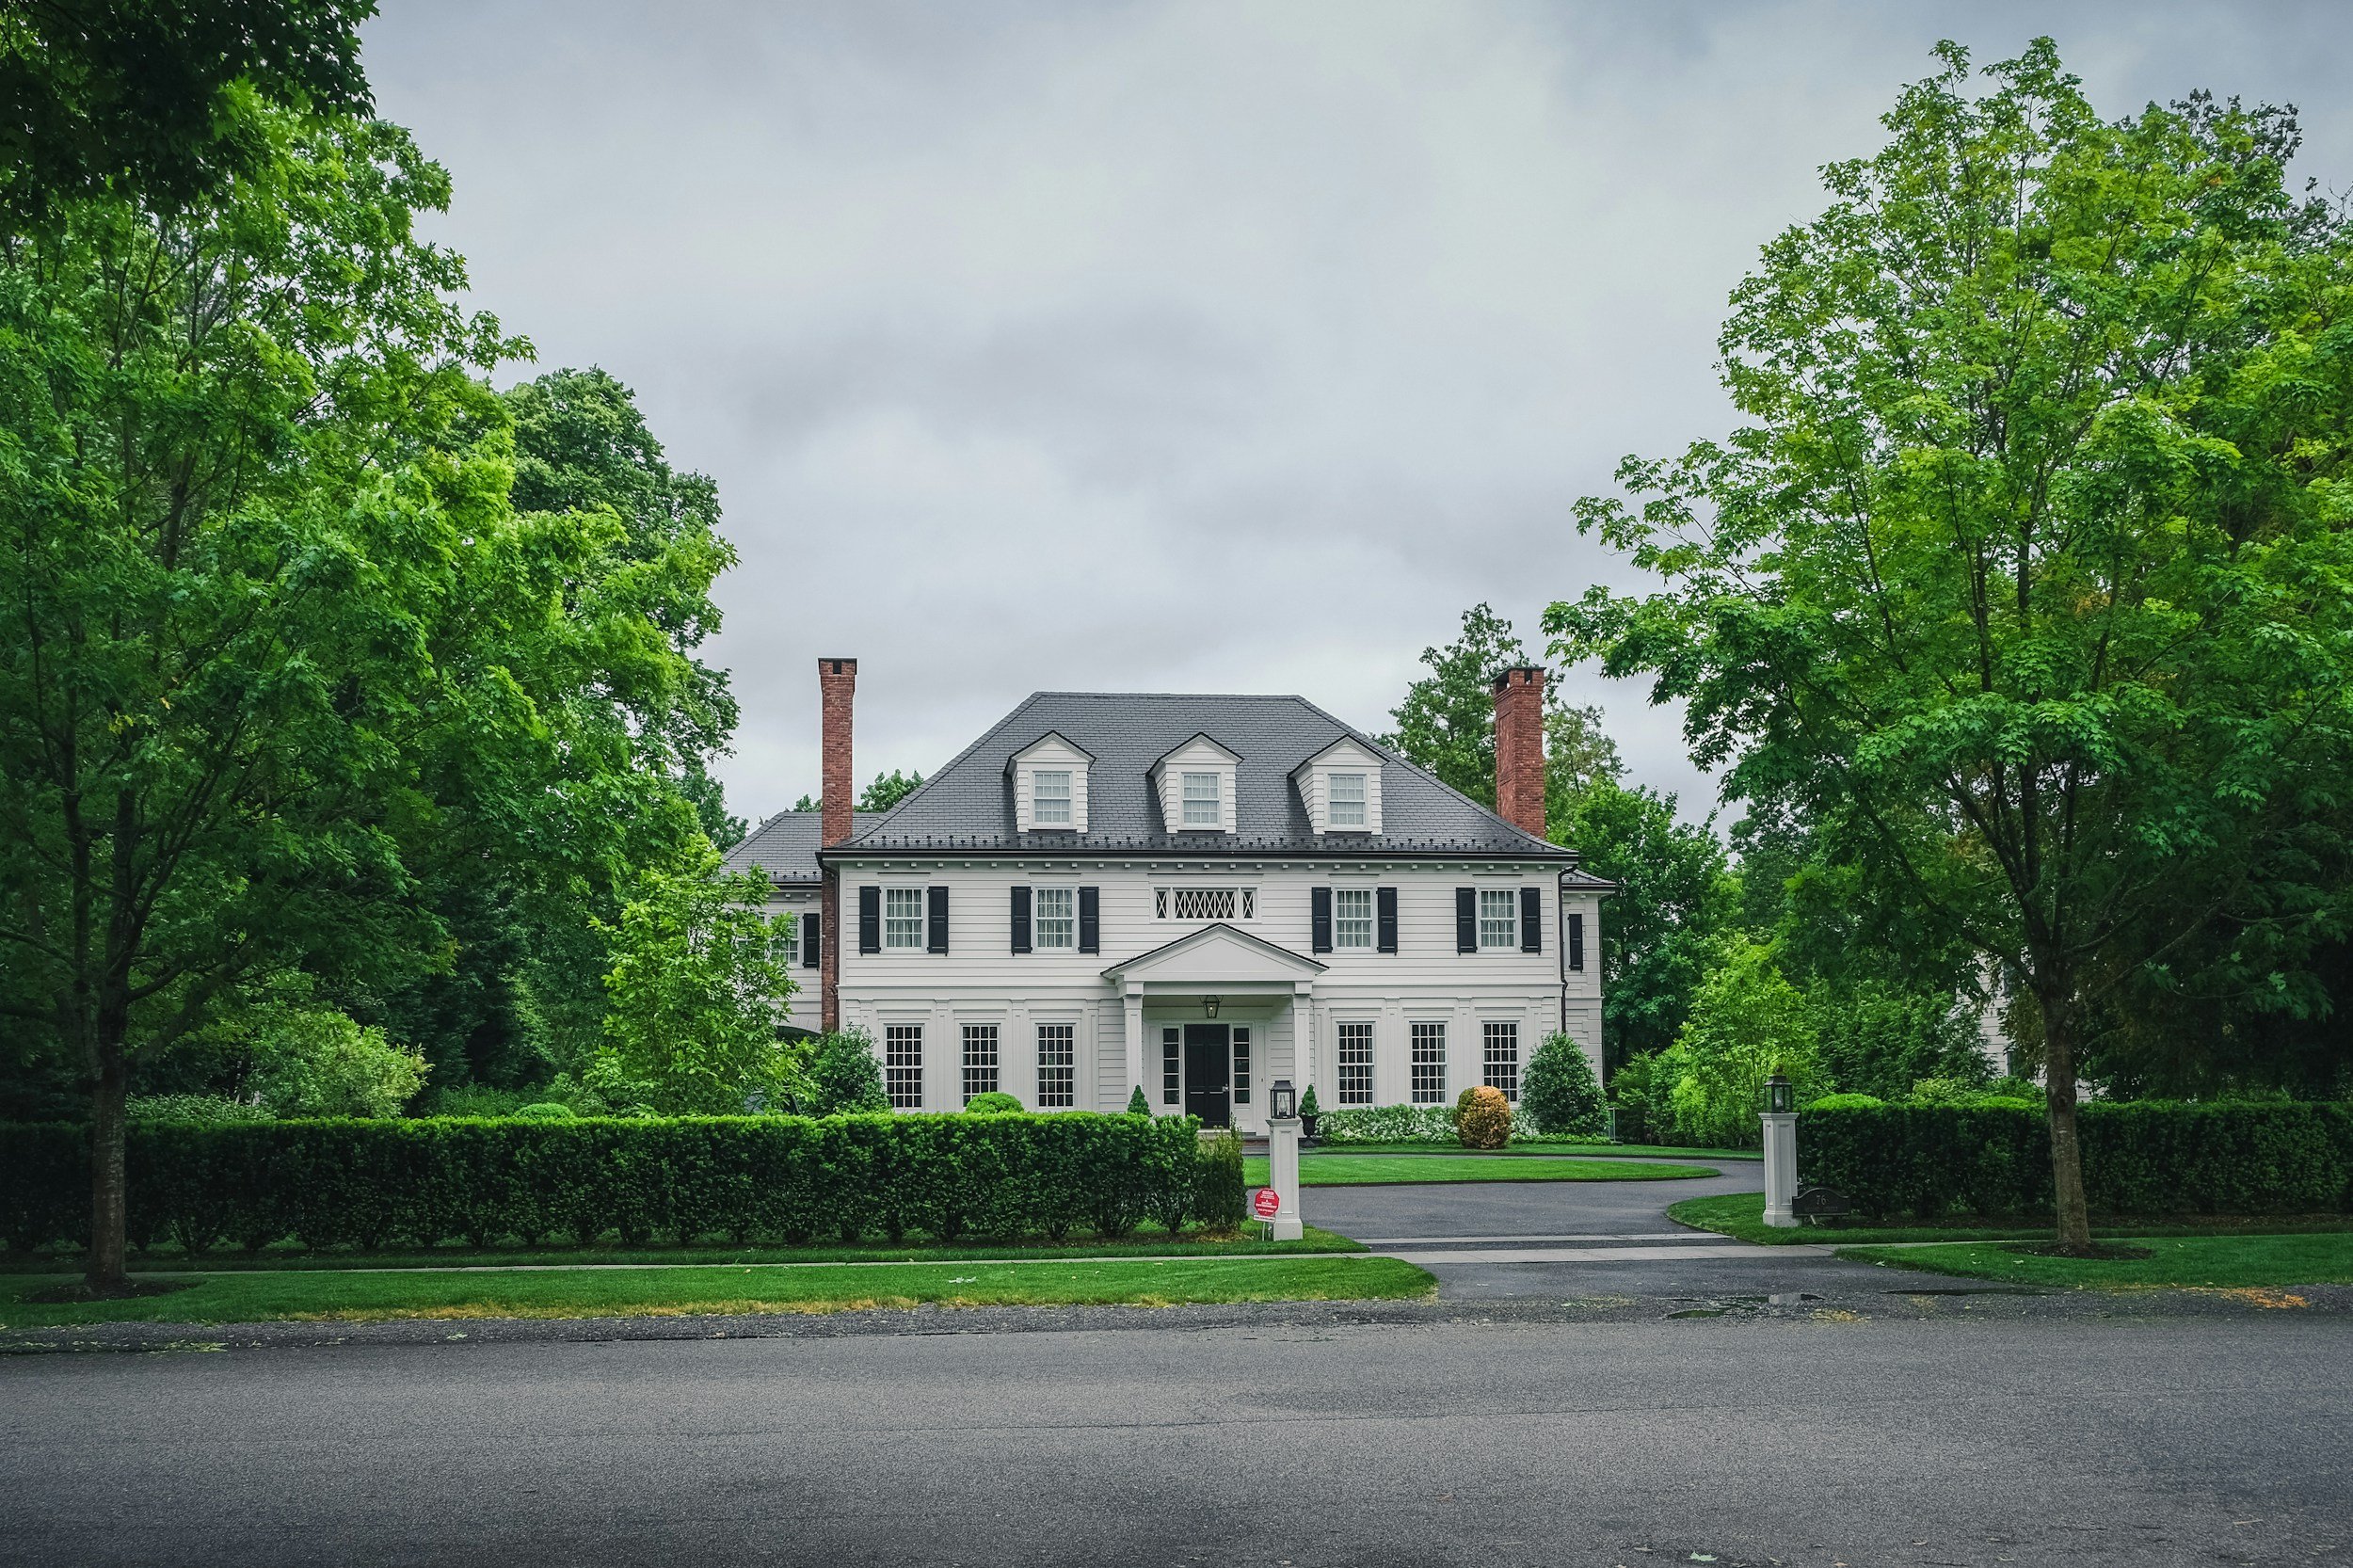
FOR HIGHER PRICED HOMES
The jumbo loan - for homes above the conforming limit.
When a home's price pushes your loan past the annual conforming limit, a jumbo loan carries you the rest of the way. It's how buyers finance higher-priced properties — more common around Vancouver and Clark County than you might expect.
$832,750
2026 CONFORMING LIMIT
10-20%
TYPICAL DOWN PAYMENT
720+
CREDIT SCORE, USUALLY
WHAT IT IS
A mortgage that goes beyond the government-backed ceiling.
Each year the Federal Housing Finance Agency sets a conforming loan limit — the largest loan Fannie Mae and Freddie Mac will buy. For 2026 that baseline is $832,750 for a one-unit home in most areas. A mortgage larger than that limit is called a jumbo loan.
Because jumbo loans exceed that ceiling, they can't be sold to the government-sponsored enterprises — the lender takes on more risk and holds them differently. In exchange, they let you finance a higher-priced home with a single loan instead of splitting it or putting down enormous cash.
The trade-off is stricter qualifying: lenders look for stronger credit, lower debt, and more reserves. But rates today are often competitive with conventional loans, and for the right buyer a jumbo is simply the clean, straightforward way to finance the home they actually want. In higher-priced pockets of Washington, that comes up more often than in rural Montana or South Dakota.
IS IT RIGHT FOR YOU?
Where a jumbo loan shines
& where to look twice.
-
A Strong Fit If...
The home you want pushes your loan above $832,750
You have strong credit and steady, well-documented income
You can put down roughly 10-20% and hold healthy reserves
You’d rather one clean loan than splitting into two
-
Worth Weighing...
Qualifying is stricter - credit, income, and reserves
Down payment and cash-reserve requirements run higher
Appraisals can be more involved for higher-value homes
Not needed if your loan lands under the conforming limit
WHAT IS NEEDED
Typical requirements at a glance.
Guidelines, not guarantees — your exact picture depends on the full application. Here's the honest ballpark.
Loan Size
Above the 2026 conforming limit of $832,750 (higher in some high-cost areas).
Credit Score
Typically 700-720+; the strongest rates favor higher scores.
Down Payment
Often 10-20%, depending on loan size and profile.
Cash Reserves
Lenders usually want several months of payments in reserve.
Debt-to-Income
Generally kept lower than conventional - often around 43% or lower.
HOW IT GOES
Jumbo, start to keys.
THE CONVERSATION
We confirm whether your price actually needs a jumbo, or whether a larger down payment keeps you conforming.
01
PRE-APPROVAL
We document income, assets, and reserves carefully - jumbo underwriting rewards a clean, complete file.
02
FIND YOUR HOME
You shop with a strong pre-approval; the appraisal confirms the higher value.
03
CLOSING
We review every figure together and you sign - one loan, no surprises.
04
STRAIGHT ANSWERS
Common questions about jumbo loans.
-
Any mortgage larger than the FHFA conforming limit — $832,750 for a one-unit home in most areas in 2026. Go one dollar over and it's a jumbo, underwritten to stricter standards.
-
Not always. They were historically, but jumbo rates today are often competitive with, and sometimes below, conforming rates. I'll show you the real comparison for your situation.
-
Commonly 10–20%, though it varies by loan size, credit, and reserves. Some scenarios allow less. We'll map what your profile supports.
-
Sometimes, yes — if you're just over the limit, putting a bit more down can keep your loan conforming and simplify qualifying. That's exactly the kind of thing we'll check first.
KEEP EXPLORING
Other Loan Types.
NO PRESSURE, NO OBLIGATION
Not sure whether your price needs a jumbo?
That’s the first thing we’ll figure out together - sometimes a small change keeps you conforming. Either way, no pressure.
CALL (360) 600-8250 - LICENSED IN WA - MT - SD - NMLS #2650609